Nelson Advisors: Grindr’s Acquisition of PurposeMed, Strategic Diversification, Unit Economics and the Architecture of Grindr Health

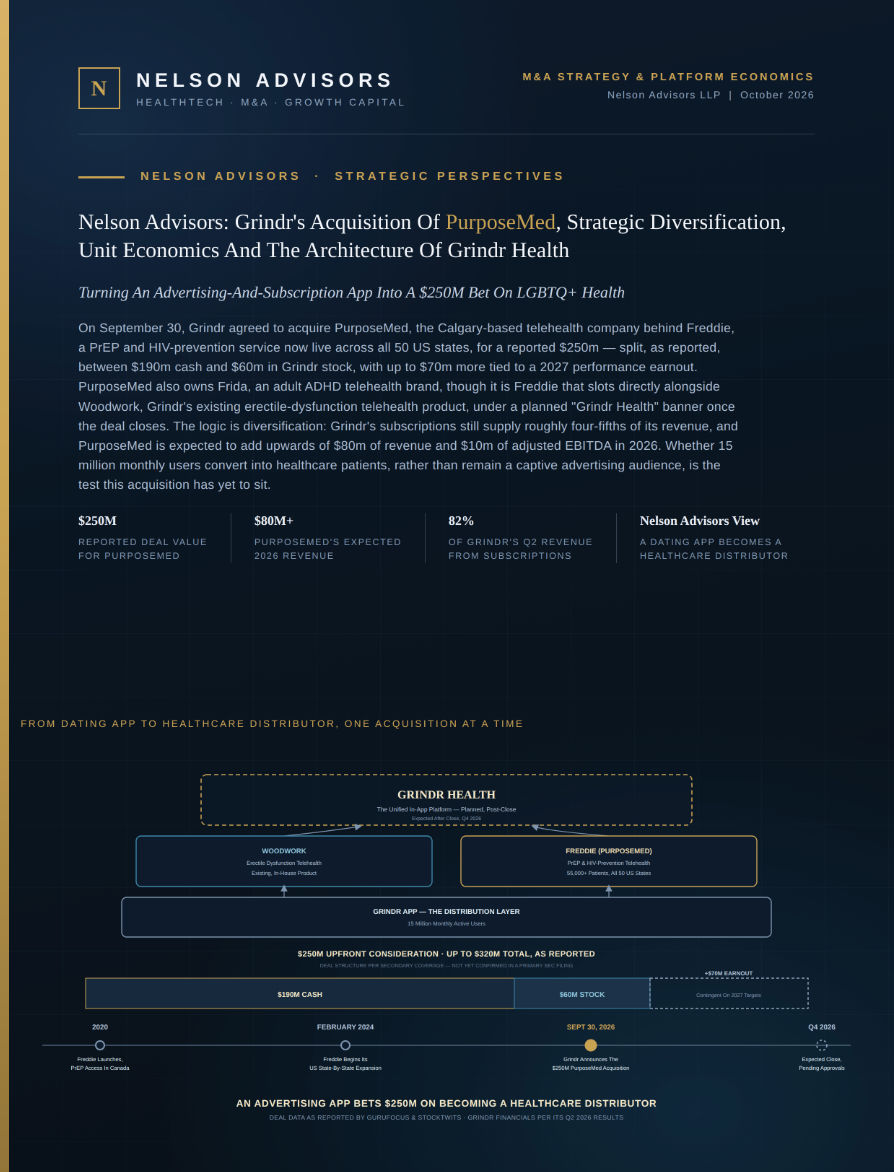
Grindr Inc. has entered into a definitive agreement to acquire PurposeMed Inc., the parent organisation of sexual health and HIV prevention telehealth provider Freddie, in a transaction establishing an upfront enterprise valuation of $250 Million with an additional performance based earn out of up to $70 Million.
This transaction represents Grindr’s first major acquisition since its founding in 2009, signaling a strategic transition from an advertising and subscription supported dating application into an integrated digital healthcare and pharmaceutical distribution platform.
By absorbing PurposeMed’s virtual care infrastructure and specialised pharmacy supply chain into its newly structured "Grindr Health" division, Grindr aims to address persistent customer acquisition bottlenecks in direct-to-consumer healthcare.
The combination establishes an ecosystem linking high intent social platform traffic to recurring preventative medicine, long-term pharmaceutical fulfilment and affirming clinical care across North America.
Transaction Structure and Valuation Mechanics
The purchase consideration is structured to balance upfront equity dilution, liquidity preservation and operational risk mitigation through milestone contingent deferred consideration.
Under the terms of the agreement, Grindr will acquire PurposeMed Inc, encompassing the Freddie brand and its partnerships with affiliated clinical networks, for an aggregate upfront base consideration of $250 million. This upfront consideration is composed of $190 million in cash financed through balance sheet liquidity and $60 million in newly issued Grindr common stock. The equity component consists of 3,851,684 common shares, pegged at an agreed valuation of $15.58 per share, representing the volume-weighted average price (VWAP) across the fifteen consecutive trading days ending September 29, 2026. These newly issued shares are subject to a mandatory 12 month post-closing lock-up agreement to ensure equity stability.
Beyond the base consideration, the transaction incorporates an earnout structure granting up to $70 million in additional cash consideration. Realisation of this capital is tied to PurposeMed achieving specified financial performance benchmarks during the fiscal year ending December 31st, 2027, with any earned proceeds payable in 2028.
Unanimously approved by the boards of directors of both entities, the transaction is slated to close in the fourth quarter of 2026, subject to customary closing conditions, pre-closing corporate reorganisation and the formal listing of consideration shares on the New York Stock Exchange. The definitive agreement includes an outside termination date of December 30th, 2026.
Financial and Structural Metric | Transaction Term | Contextual Multiples and Parameters |
Upfront Consideration | $250.0 million | $190.0 million cash / $60.0 million equity |
Common Equity Issued | 3,851,684 shares | Issued at $15.58 VWAP (15-day period to Sept 29, 2026) |
Contingent Cash Earnout | Up to $70.0 million | Payable in 2028 based on FY 2027 operating targets |
Maximum Potential Deal Value | $320.0 million | Inclusive of maximum earnout achievement |
PurposeMed Standalone FY 2026E Revenue | >$80.0 million | Target operational projection |
PurposeMed Standalone FY 2026E Adj. EBITDA | >$10.0 million | Target operational projection |
Implied Upfront Revenue Multiple | ~3.13x | Based on $250 million base against $80 million run-rate |
Implied Upfront EBITDA Multiple | <25.0x | Based on $250 million base against $10 million run-rate |
Target Closing Date | Q4 2026 | Outside contract long-stop date: December 30, 2026 |
On a standalone basis, PurposeMed anticipates generating full year 2026 revenue exceeding $80 million alongside more than $10 million in Adjusted EBITDA. Grindr’s upfront enterprise outlay values the asset at approximately x3.13 times forward revenues. Grindr management projects the transaction to have an immaterial net impact on consolidated fiscal 2026 earnings due to year end closing mechanics and ongoing capital expenditures required to expand clinical and pharmacy infrastructure in the United States.
However, the business is modelled to be immediately accretive to consolidated Adjusted EBITDA dollar totals upon closing, transitioning to meaningful EBITDA margin accretion in fiscal 2027 as patient volume scales across the platform.
PurposeMed’s Clinical Scope and Operating Infrastructure
PurposeMed was established in Calgary, Canada, in 2019 by Dr. Husein Moloo, Pete MacLeod, Amaan Banwait, and Dr. Caley Shukalek with an operating mandate to improve healthcare access for marginalised and geographically isolated patient populations. The organisation manages an integrated ecosystem of virtual care brands supported by a proprietary network of more than 200 healthcare professionals, care coordinators, and engineers. Rather than serving solely as a telehealth brokerage, PurposeMed operates closed-loop fulfilment by pairing clinical consultations with physical pharmaceutical distribution.
The enterprise delivers care across three primary virtual operating units, supported by an internal and partnered distribution channel known as Affirming Care Pharmacy. Affirming Care Pharmacy maintains centralised fulfilment centres in Canadian hubs, including Calgary, Mississauga and Toronto, as well as United States logistics centres in Los Angeles, New York City, and San Antonio. These fulfillment hubs manage temperature sensitive, discreet, and specialised drug delivery direct to consumer residences.
Operating Unit | Primary Clinical Mandate | Geographic Footprint and Care Model |
Freddie | HIV prophylaxis (PrEP), STI diagnostic screenings, recurring preventative care | All 50 U.S. states and D.C.; five Canadian provinces; telehealth and lab integration |
Frida | Adult attention-deficit/hyperactivity disorder (ADHD) diagnosis and continuous therapy | National Canadian coverage; structured psychiatric assessments and medical treatment |
Foria Clinic | Gender-affirming care and hormone replacement therapy for trans and non-binary adults | Virtual clinical consultations, continuous endocrinological monitoring across Canada |
Affirming Care Pharmacy | Specialty dispensing, medication coordination, mail-order fulfillment | Six fulfillment hubs: Calgary, Mississauga, Toronto, Los Angeles, New York, San Antonio |
The flagship asset within the portfolio is Freddie, which serves as the largest online HIV prevention clinic in Canada and expanded into the United States market in 2024. Holding clinical network partnerships and professional licensure covering all 50 U.S. states and the District of Columbia, Freddie has provided specialised sexual health consultations to more than 55,000 patients across North America.
Freddie’s care delivery integrates automated laboratory requisitioning for baseline renal and STI screenings, asynchronous and synchronous telehealth evaluations with licensed clinician and automated 90 day medication fulfilment. Clinical modelling published by the organisation estimates that its active patient base prevents roughly 385 new HIV transmissions annually surpassing one prevented transmission per calendar day, which generates between $270 million and $580 million in averted direct lifetime treatment costs across North American health systems each year.
Strategic Rationale and the Architecture of Grindr Health
Grindr’s capital allocation toward healthcare represents a strategic effort to overcome monetisation ceilings typical of consumer social applications. Grindr’s core subscription and advertising operations have demonstrated underlying strength, highlighted by a second quarter 2026 revenue expansion of 33% year over year to $138 million and upgraded full year guidance targeting approximately $540 million in revenue and $232 million in Adjusted EBITDA.
Under Chief Executive Officer George Arison, the platform increased paying subscriber penetration from under 6% in 2022 to above 9% by 2026. However, maintaining elevated growth rates solely through consumer dating subscriptions faces eventual resistance. The company's long-term plan targets a three phase transition: first, optimising basic paywall conversion; second, introducing premium tiers such as the AI driven "Edge" offering and third, expanding horizontally into high utility ancillary services through the "Global Gayborhood in Your Pocket" model.
Grindr Health functions as the foundational mechanism of this third phase, structured around three complementary clinical pillars. The first pillar covers performance medications, initially established through Grindr’s cash-pay brand "Woodwork" in partnership with digital health vendor OpenLoop to provide discrete treatments for erectile dysfunction, metabolic therapies including GLP-1 agonists and peptides. The second pillar addresses infectious disease prevention and management, centred on Freddie’s PrEP infrastructure, routine diagnostics and specialty dispensing. The third pillar encompasses affirmative primary care, mental health support, and longevity treatments, utilising the underlying clinical capabilities of PurposeMed’s Frida and Foria verticals.
This strategy addresses the high customer acquisition costs that challenge standalone direct to consumer digital health providers. Traditional digital clinics face high costs bidding for relevant keywords across generic digital advertising channels. In contrast, Grindr has an audience of nearly 16 million monthly active users, allowing it to distribute health offerings within its own ecosystem. The platform holds concentrated mindshare among populations clinically indicated for HIV prophylaxis, with roughly 400,000 domestic U.S. users voluntarily displaying their active PrEP status directly on their public profile fields.
Across the broader United States market, approximately 650,000 individuals actively utilise PrEP, while epidemiologic consensus estimates that 2.2 million individuals could clinically benefit from preventative therapy, leaving a documented treatment gap of over 1.5 million people.
By embedding Freddie into its core interface, Grindr provides an in app pathway allowing users to assess health insurance eligibility, interface with affirmative medical providers, complete localised diagnostic testing and arrange home delivery of therapy without navigating disjointed external medical systems. This ecosystem captures the economic value of the fulfilment chain, converting passive platform engagement into recurring healthcare revenue.
Unit Economics and Operating Leverage
The operating economics of pharmaceutical delivery and ongoing telehealth monitoring diverge significantly from software subscriptions, yielding higher gross customer monetisation offset by physical fulfilment expenses. While Grindr's software subscriptions yield elevated gross margins on modest recurring fees, digital health platforms capture substantial annual spending across clinical and pharmaceutical services.
Grindr projects that its combined domestic telehealth consultation and pharmacy operation will generate more than $400 in monthly revenue per active patient. This corresponds to an annual value exceeding $4,800 per active, compliant patient.
Under the provisions of the Affordable Care Act and associated United States Preventive Services Task Force (USPSTF) Grade A recommendations, PrEP medications alongside mandated quarterly clinical reviews and laboratory panels must be covered by commercial health insurers without cost-sharing.
As a result, Freddie navigates commercial insurance reimbursement and manufacturer copay assistance programs, minimising out of pocket costs for insured patients while securing recurring revenue.
By operating its own pharmacy dispensing network through Affirming Care Pharmacy, Grindr captures dispensing margins that would otherwise be retained by external retail pharmacy networks or pharmacy benefit managers.
Financial Parameter | Grindr Standalone Operations (FY 2026E) | PurposeMed Standalone Operations (FY 2026E) | Combined Target Model at Operational Scale |
Top-Line Revenue | ~$540.0 million | >$80.0 million | Diversified Core + High-Volume Clinical Base |
Adjusted EBITDA | ~$232.0 million | >$10.0 million | Initial Margin Dilution Yielding Dollar Scale |
Adjusted EBITDA Margin | >40.0% | Mid-Teens (~12.5%) | Approaching >40.0% at Structural Maturity |
Primary Revenue Streams | User Subscriptions & In-App Ads | Telehealth Consults & Pharmacy Rx | Recurring Software Tiers & Healthcare Billing |
Monetisation Velocity | Monthly Software ARPU Metrics | Discrete Transactional Reimbursements | >$4,800 Annual Revenue per Active Patient |
Platform Population | ~16M Monthly Active Users | >55,000 Historical Total Patients | Corporate Goal of 10M Connected by 2028 |
PurposeMed currently generates an Adjusted EBITDA margin in the mid teens, reflecting investments required to establish clinical networks and license pharmacy facilities across North America. Grindr management has noted that scaling healthcare margins to meet the core business target of over 40% will depend on volume driven operating leverage rather than corporate cost reductions. Fulfilling physical prescriptions and conducting medical consultations requires direct clinical labour that cannot be automated in the same manner as software features.
Consequently, long term margin expansion relies on patient onboarding through Grindr's conversion funnels. As clinical volume scales, fixed infrastructure costs are absorbed more efficiently and higher medication volumes improve pharmacy procurement terms, driving margins closer to corporate levels.
Regulatory Governance, Structural Firewalls and Data Privacy
Integrating clinical medical services into a social and dating platform requires adherence to healthcare regulations and strict data privacy protocols. The acquisition occurred alongside scrutiny over historical data governance practices across consumer applications, highlighting the importance of structural firewalls between social features and medical data.
In September 2026, Grindr resolved a High Court group action lawsuit in the United Kingdom, agreeing to pay £26 million (approximately $35.2 million) across roughly 12,000 claimants to settle allegations regarding historical data disclosures. The litigation stemmed from commercial practices prior to April 2020, during which user profile data, including user disclosed HIV statuses and last testing dates, were transmitted to external analytics providers, including Apptimize and Localytics, without sufficient affirmative user consent.
These practices also resulted in regulatory enforcement from the Norwegian Data Protection Authority (Datatilsynet) and contributed to historical divestment mandates issued by the Committee on Foreign Investment in the United States (CFIUS).
To address these compliance requirements, Grindr Health is structured around technical and organisational data firewalls. PurposeMed’s clinical operations function as covered entities subject to the Health Insurance Portability and Accountability Act (HIPAA) in the United States and the Personal Information Protection and Electronic Documents Act (PIPEDA) in Canada.
Under this architecture, Protected Health Information (PHI), such as medical records, lab findings, clinical interactions and pharmaceutical orders, remains segregated from Grindr’s core advertising systems and public profile databases. Participation is structured as voluntary: Grindr users can browse health offerings without their medical history connecting to their social profile, and clinical patients can use Freddie independently of the dating platform. Additionally, patient interfaces must exclude tracking scripts and advertising identifiers to remain compliant with updated Federal Trade Commission (FTC) Health Breach Notification rules.
Beyond data governance, expanding clinical delivery across North America introduces operational and regulatory considerations:
Compliance with Corporate Practice of Medicine (CPOM) regulations across key states, which prevent non-physician commercial entities from directly employing clinicians or directing care decisions, requiring PurposeMed to maintain physician-owned Professional Corporation (PC-MSO) structures.
Management of state by state pharmacy distribution licenses to ensure compliance with multi-jurisdictional shipping, localised dispensing and temperature-controlled storage standards.
Monitoring shifts in federal reimbursement frameworks, as legal challenges to ACA preventative care mandates could influence commercial insurance coverage models and copay assistance structures for PrEP over time.
Strategic Outlook
Grindr’s $250 million acquisition of PurposeMed marks a major shift in the company's business model, establishing a base to diversify beyond consumer advertising and dating subscriptions. By combining its platform distribution with PurposeMed’s licensed clinical networks, mail-order pharmacies and virtual care platforms, Grindr addresses customer acquisition hurdles that often challenge digital health providers.
The long-term success of the transaction will depend on execution across two main fronts.
First, PurposeMed must scale toward Grindr’s corporate Adjusted EBITDA margins of over 40% by expanding patient volume to absorb fixed clinical and pharmacy infrastructure expenses. Second, the company must maintain operational and technical separation between Grindr’s consumer app and its regulated medical systems to ensure compliance with HIPAA, PIPEDA, and FTC data guidelines.
If Grindr manages these operational and compliance requirements, Grindr Health could reshape the company's financial profile, transforming a specialized dating app into an integrated digital healthcare and pharmaceutical provider for the LGBTQ+ demographic.
Nelson Advisors > European Healthcare Technology Investment Banking
Nelson Advisors specialise in Mergers and Acquisitions for European HealthTech, MedTech, Digital Health, Healthcare IT, Healthcare AI companies in the Lower to Mid Market ranging from $25M to $250M EV. www.nelsonadvisors.co.uk
Healthcare.Digital is the Google News approved HealthTech and MedTech Thought Leadership platform for Nelson Advisors, positioning them as a specialised authority on European Healthcare Technology M&A and strategic corporate development. https://www.healthcare.digital
Nelson Advisors publish Europe's Leading Healthcare Technology Investment Banking Newsletter every week, join 5000+ HealthTech and MedTech subscribers today! https://lnkd.in/e5hTp_xb
Healthcare.Digital serves as a research platform for Nelson Advisors’ perspectives on deals, valuations and structural shifts reshaping Global Digital Health, MedTech, Healthcare AI and Health IT. https://www.healthcare.digital
Nelson Advisors is one of Europe's leading mergers and acquisitions advisory firms, exclusively dedicated to the dynamic and rapidly evolving healthcare technology sector. With a deep understanding of market dynamics and technological advancements, they empower innovative HealthTech companies and strategic investors to navigate complex transactions and achieve their growth ambitions. www.nelsonadvisors.co.uk
#NelsonAdvisors #HealthTech#MedTech#DigitalHealth #HealthIT #Cybersecurity #HealthcareAI #FemTech#ConsumerHealth #Mergers #Acquisitions #Partnerships #Growth #Strategy #NHS #UK #Europe #USA #Canada#Commonwealth#CorporateDivestitures #VentureCapital #PrivateEquity #Founders #SeriesA #SeriesB #Founders #SellSide #TechAssets #Fundraising #BuildBuyPartner #GoToMarket #PharmaTech #Genomics
Nelson Advisors L
Hale House, 76-78 Portland Place, Marylebone, London, W1B 1NT
Meet Nelson Advisors @ Events in 2026
Digital Health Rewired > March 2026 > Birmingham, UK
NHS ConfedExpo > June 2026 > Manchester, UK
HLTH Europe > June 2026, Amsterdam, Netherlands
HIMSS AI in Healthcare > July 2026, New York, USA
Bits & Pretzels > September 2026, Munich, Germany
HealthInvestor Healthcare Summit > September 2026, London, UK
World Health Summit 2026 > October 2026, Berlin, Germany
HLTH USA 2026 > October 2026, USA
Global Health Exhibition 2026 > October 2026, Riyadh, Saudi Arabia
Web Summit 2026 > November 2026, Lisbon, Portugal
MEDICA 2026 > November 2026, Düsseldorf, Germany
Leaders in Health Summit 2026 > November 2026, London, UK
Venture Capital World Summit > December 2026, Toronto, Canada
Meet Nelson Advisors @ Events in 2027
Digital Health Rewired > March 2027 > Birmingham, UK
Barclays Health Elevate > March 2027, London, UK
NHS ConfedExpo > June 2027 > Manchester, UK
HLTH Europe > June 2027, Amsterdam, Netherlands


Comments