Nelson Advisors: Capitalising on Healthcare AI Infrastructure - Sopris Capital’s Acquisition of Blackford Analysis and the Strategic Realignment of Longitudinal Care

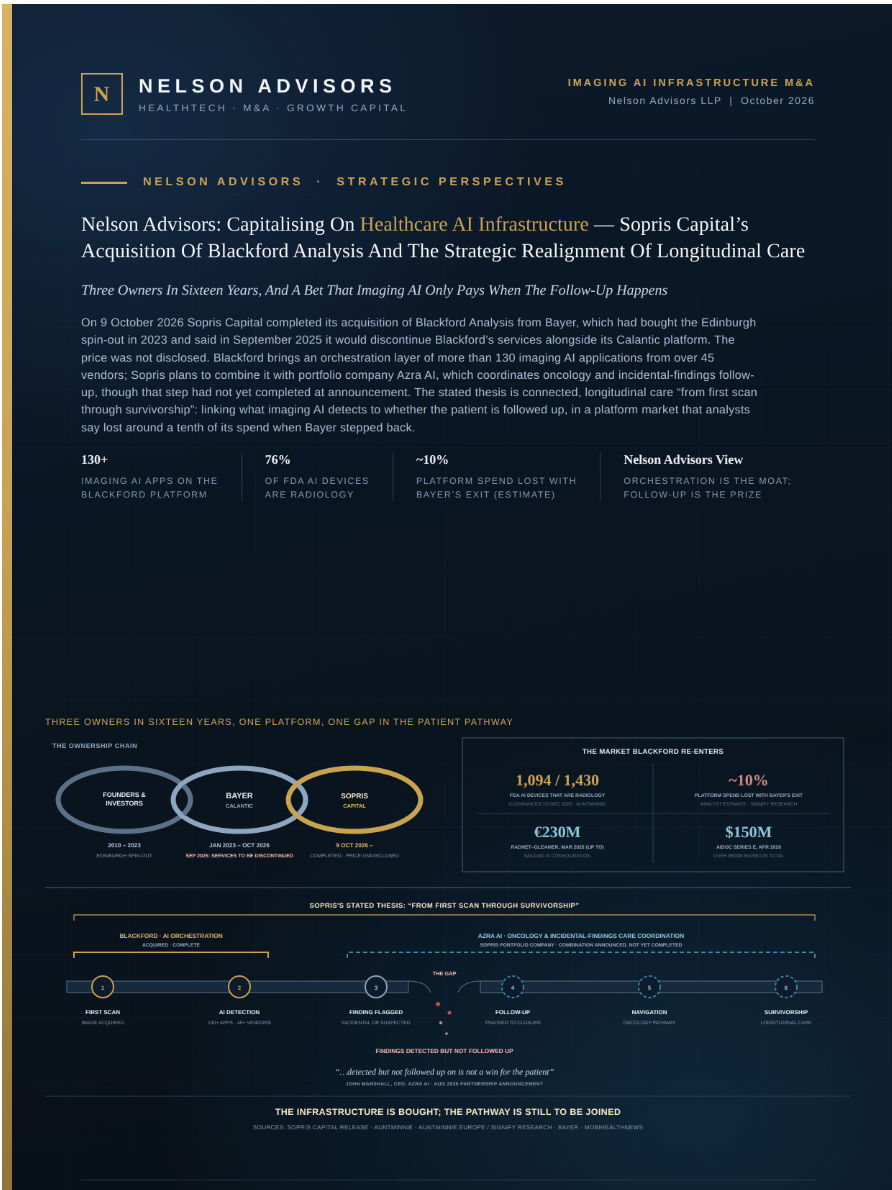
Transaction Mechanics and Corporate Architecture
On October 9th, 2026, private growth equity firm Sopris Capital finalised the acquisition of medical imaging artificial intelligence orchestration provider Blackford Analysis Ltd. from life sciences conglomerate Bayer AG for an undisclosed purchase price.
Under the agreed transaction structure, the Miami- and Colorado based investment firm plans to fold Blackford into Azra AI, a core portfolio company focused on automated oncology clinical pathways and care navigation, within several weeks of closing.
Transaction Dimension | Operational and Financial Specification |
Acquiring Entity | Sopris Capital Associates |
Divesting Entity | Bayer AG |
Acquired Entity | Blackford Analysis Ltd. |
Operating Integration Platform | Azra AI (Sopris Capital portfolio company) |
Deal Value | Undisclosed financial consideration |
Closing Date | October 9, 2026 |
Post-Transaction Entity Structure | Autonomous legal operating entity with hubs in Edinburgh and the United States |
Key Executive Leadership | Abinav Sankar (Managing Partner, Sopris), John Marshall (CEO, Azra AI), James Holroyd (Managing Director, Blackford) |
Blackford Analysis will maintain its distinct corporate identity as an independent legal operating entity, preserving its engineering and commercial hubs in Edinburgh, Scotland, and across the United States. This dual region structure is designed to safeguard operational continuity across Blackford’s channel network, maintaining service levels for hospital networks, original equipment manufacturer (OEM) partners, and third-party algorithm vendors. Blackford Managing Director James Holroyd will continue to lead the enterprise’s imaging infrastructure operations, coordinating closely with Azra AI Chief Executive Officer John Marshall and Sopris Managing Partner Abinav Sankar.
The acquisition represents the balance sheet formalisation of a strategic commercial relationship established between the two software companies earlier in the year. On August 5th 2026, Azra AI and Blackford entered into an enterprise partnership designed to connect imaging AI detections directly with clinical care coordination.
Moving from a contractual partnership to unified equity ownership enables Sopris Capital to centralise product roadmaps, combine software development resources and execute bundled commercial offerings across enterprise healthcare systems.
Evolution and Divestiture of Bayer’s Digital Imaging Platform
The divestiture of Blackford Analysis marks the conclusion of Bayer AG's initiative to build and operate an enterprise digital radiology marketplace. Founded in 2010 as a computational spin-out from the University of Edinburgh, Blackford initially developed image registration and processing software before pioneering the sector's first medical imaging AI orchestration platform in 2016.
In February 2023, Bayer acquired Blackford outright to serve as the core foundational layer for its Calantic Digital Solutions suite. Life sciences market observers initially theorised that multinational pharmaceutical and medical device manufacturers could leverage long standing commercial relationships, particularly hospital supply contracts for radiology contrast media and mechanical power injectors—to drive the cross-selling of enterprise software platforms.
Strategic Milestone | Date | Operational Realisation |
Platform Inception | 2010 | Founded as a University of Edinburgh spin-out focused on imaging computation. |
Marketplace Launch | 2016 | Commercial release of the industry's first vendor-neutral radiology AI orchestration platform. |
Bayer Acquisition | February 2023 | Acquired by Bayer AG to anchor the Calantic Digital Solutions platform ecosystem. |
Strategic Deprioritization | September 2025 | Bayer announces market exit from Calantic and moves to wind down or divest Blackford. |
Thynk Health Acquisition | April 2026 | Azra AI acquires Thynk Health to incorporate programmatic lung screening and incidental finding capture. |
Commercial Alliance | August 2026 | Azra AI and Blackford execute an enterprise care navigation and imaging partnership. |
Sopris Capital Purchase | October 2026 | Sopris Capital completes the purchase from Bayer, initiating the operational combination with Azra AI. |
The commercial thesis supporting pharmaceutical ownership of digital health platforms faced persistent headwinds. Radiology AI platform providers experienced slower than projected clinical adoption across health systems, prolonged institutional procurement timelines, and elevated software maintenance overhead. Concurrently, broader corporate restructuring initiated under Bayer Chief Executive Officer Bill Anderson drove a strategic reallocation of capital back toward core pharmaceutical pipelines, consumer therapeutics and high margin contrast injection devices.
By September 2025, Bayer publicly confirmed its decision to deprioritise its digital platform business, shutting down Calantic Digital Solutions and initiating the wind down and divestiture of Blackford Analysis. The pharmaceutical company signalled that it would transition active Blackford agreements into alternative arrangements or direct contracts with third-party vendors. Sopris Capital capitalised on Bayer's strategic retreat, acquiring the established software asset at an attractive valuation to anchor its own healthcare IT portfolio.
Technical Convergence: Bridging Upstream Orchestration and Downstream Care Pathways
The primary operational rationale for uniting Blackford Analysis and Azra AI lies in overcoming a systemic breakdown in healthcare IT: the divide separating diagnostic image interpretation from downstream clinical follow up. When algorithms identify critical abnormalities in isolation, clinical value often dissipates due to administrative gaps and siloed electronic health record workflows.
Blackford operates upstream at the point of diagnostic generation. Its vendor-neutral orchestration platform integrates directly with hospital Picture Archiving and Communication Systems (PACS), Radiology Information Systems (RIS), and Vendor Neutral Archives (VNAs). By handling DICOM metadata routing, containerised inference execution, and user interface harmonisation, Blackford provides access to more than 130 clinically validated applications from over 45 partner vendors spanning eight clinical service areas. This architecture spares enterprise IT teams the technical burden of deploying isolated servers, managing bespoke API interfaces, and maintaining individual cybersecurity clearances for dozens of standalone algorithms.
Azra AI operates downstream across longitudinal patient care. Operating across hundreds of healthcare facilities, Azra AI utilizes proprietary natural language processing (NLP) models to parse unstructured clinical text, pathology narratives, and radiology impressions.
The platform flags malignant disease, automates cancer registry submissions, and routes patients to oncology nurse navigators and multidisciplinary specialists. Through its April 2026 acquisition of Thynk Health, Azra AI extended these capabilities to lung cancer screening protocols and incidental finding management, ensuring that patients flagged for anomalous pulmonary or cardiovascular findings remain enrolled in proper follow-up regimens.
System Dimension | Blackford Analysis Platform | Azra AI Enterprise Platform |
Workflow Locus | Upstream: Image capture, PACS routing, algorithm orchestration, and reading workflows. | Downstream: Care coordination, clinical navigation, tumor boards, and registry reporting. |
Data Ingestion Types | Pixel-level DICOM files, imaging series, modality worklists, and spatial segmentations. | Unstructured clinical narratives, radiology impressions, pathology summaries, and EHR records. |
Algorithmic Ecosystem | Vendor-neutral marketplace (130+ partner models across 45+ software developers). | Native clinical NLP models, clinical pathway workflows, and agentic clinical research matching. |
Target Clinical Users | Diagnostic radiologists, imaging technologists, PACS administrators, and health system CIOs. | Oncology nurse navigators, service line leaders, tumor registrars, and clinical trial coordinators. |
Host System Integrations | PACS, RIS, VNAs, imaging modalities, and diagnostic workstations. | Electronic Health Records (EHR), cancer registry systems, and clinical trial databases. |
Primary Clinical Deliverables | Radiologist worklist triage, computer-aided detection overlays, and quantitative organ measurements. | Lost-to-follow-up prevention, automated specialist referrals, and accelerated time-to-treatment. |
By combining Blackford's upstream pixel orchestration with Azra AI's downstream text parsing and navigation workflows, the merged entity creates a closed-loop clinical pathway. Rather than waiting for a radiologist's finalised dictated narrative to pass into the EHR before initiating navigation protocols, Azra AI can ingest real-time inference alerts directly from Blackford’s image-analysis pipeline. This technical synchronisation accelerates multidisciplinary clinical intervention from the moment an initial scan is acquired through survivorship care management.
Ecosystem Relationships, Distribution Rails and Partner Neutrality
A critical requirement in enterprise healthcare software mergers is preserving ecosystem neutrality. In platform marketplace models, third-party software developers and hardware distributors depend on the orchestration layer remaining strictly vendor-neutral, ensuring that partner algorithms are evaluated and routed based on clinical utility rather than corporate bias.
Sopris Capital addressed this industry concern by keeping Blackford as a separate legal entity, preserving its existing operating teams, engineering centres, and customer facing support infrastructure in Scotland and the United States. This separation allows Blackford to protect its established OEM distribution agreements, such as its ongoing integration within GE HealthCare's Centricity and TruePACS architectures. Through these OEM relationships, hardware manufacturers deliver unified AI marketplaces directly to hospital radiology departments without having to develop or maintain bespoke middleware layers.
Healthcare Ecosystem Partner | Operational Value Proposition | Post-Acquisition Structural Continuity |
Original Equipment Manufacturers (OEMs) | Embedded platform layer powering imaging workstations without internal software engineering debt. | Existing commercial distribution agreements and software support pipelines remain fully operational. |
Independent Software Vendors (ISVs) | Scalable distribution channel reaching hospital networks through a single standardized integration. | Preserved marketplace neutrality; Azra AI's care orchestration does not compete with partner imaging models. |
Hospital Radiology Departments | Unified deployment interface preventing workflow fragmentation and multiple IT security reviews. | Continuous uptime with zero operational disruption to active PACS/RIS clinical routing workflows. |
Oncology and Specialty Service Lines | Automated identification of at-risk patients requiring complex follow-up and multi-specialty intervention. | Bi-directional data sharing between imaging algorithms and nurse navigation worklists. |
For third party algorithm vendors, Sopris Capital's intervention provides balance-sheet stability following the turbulence of Bayer's announced marketplace withdrawal. Because Azra AI specialises in natural language care management and cancer registry automation rather than computer-vision diagnostics, the integration does not cannibalise the products of Blackford's independent software vendors. Instead, it broadens the clinical utility of partner models by demonstrating to hospital leadership that algorithm detections directly trigger actionable, revenue-protecting clinical follow up.
Structural Maturation in the Healthcare AI Market
The transaction between Sopris Capital and Bayer illustrates a major transition in digital health financing: the shift from funding narrow, disconnected diagnostic point solutions to backing integrated workflow and infrastructure layers.
During the initial growth phase of healthcare AI, venture investment flowed predominantly into isolated algorithmic point solutions designed to identify specific clinical pathologies, such as coronary artery calcifications, wrist fractures, or acute intracranial hemorrhages. Although numerous developers secured regulatory clearances, they struggled with distribution, IT procurement resistance, and inconsistent reimbursement structures. Hospital chief information officers actively resisted maintaining independent contracts, customised cybersecurity assessments, and bespoke user interfaces for individual, single-purpose applications.
While the emergence of orchestration marketplaces resolved these integration headaches, pure distribution platforms faced difficult unit economics. Operating purely as middleware brokers, marketplace platforms were constrained by low revenue margins derived from algorithms that were themselves difficult to monetise, creating the commercial pressures that ultimately led to Bayer’s exit.
Market Evolution Phase | Core Technological Focus | Commercial and Revenue Model | Primary Industry Limitations |
Phase 1: Proliferation of Point Solutions | Narrow, pathology-specific computer-vision diagnostic algorithms. | Individual SaaS subscriptions sold directly to radiology departments. | Severe procurement friction, alert fatigue, and lack of standalone reimbursement. |
Phase 2: Aggregated Distribution Platforms | Centralized orchestration middleware and multi-vendor marketplaces. | Transactional licensing cuts, marketplace fees, and platform maintenance contracts. | Thin broker margins; commercial exposure to slow algorithmic adoption. |
Phase 3: Closed-Loop Clinical Infrastructure | Unified upstream diagnostic orchestration paired with longitudinal care navigation. | Enterprise health system licenses tied to patient retention and operational return-on-care. | High integration complexity requiring cross-departmental alignment. |
The modern healthcare AI market demands that diagnostic algorithms demonstrate a measurable return-on-investment tied to health system operations and service line retention. Modern hospital margins depend heavily on complex procedural service lines, particularly oncology, structural cardiology and surgical intervention. When an incidental finding identified during an emergency department scan is lost to follow-up, health systems face clinical liabilities and lose downstream procedural revenue if the patient seeks care elsewhere.
By unifying Blackford’s diagnostic orchestration layer with Azra AI’s automated tracking and care coordination tools, Sopris Capital aligns its software architecture with health system economics. The combined enterprise platform captures long-term market value not merely by surfacing an image finding to a reading radiologist, but by orchestrating the patient's entire clinical pathway through treatment and survivorship.
Strategic Outlook and Market Implications
Sopris Capital’s acquisition and integration of Blackford Analysis provides a compelling framework for private equity consolidation across healthcare technology.
The deal highlights the differing operational mandates between diversified pharmaceutical conglomerates and agile mid market growth investors. Large life science organisations often struggle to support the rapid development cycles and specialised sales motions required for enterprise healthcare software. By contrast, investment firms like Sopris Capital can acquire carved-out digital assets at attractive valuations and integrate them into established portfolio companies to unlock operational synergies.
Furthermore, the transaction demonstrates that long-term enterprise value in clinical AI will belong to platforms that link diagnostic detection directly with longitudinal patient management.
As health systems continue to consolidate their enterprise IT vendors, platforms that automate the entire care trajectory from initial diagnostic imaging capture to navigation, therapy, and survivorship tracking will hold a decisive competitive advantage in modern digital health.
Nelson Advisors > European Healthcare Technology Investment Banking
Nelson Advisors specialise in Mergers and Acquisitions for European HealthTech, MedTech, Digital Health, Healthcare IT, Healthcare AI companies in the Lower to Mid Market ranging from $25M to $250M EV. www.nelsonadvisors.co.uk
Healthcare.Digital is the Google News approved HealthTech and MedTech Thought Leadership platform for Nelson Advisors, positioning them as a specialised authority on European Healthcare Technology M&A and strategic corporate development. https://www.healthcare.digital
Nelson Advisors publish Europe's Leading Healthcare Technology Investment Banking Newsletter every week, join 5000+ HealthTech and MedTech subscribers today! https://lnkd.in/e5hTp_xb
Healthcare.Digital serves as a research platform for Nelson Advisors’ perspectives on deals, valuations and structural shifts reshaping Global Digital Health, MedTech, Healthcare AI and Health IT. https://www.healthcare.digital
Nelson Advisors is one of Europe's leading mergers and acquisitions advisory firms, exclusively dedicated to the dynamic and rapidly evolving healthcare technology sector. With a deep understanding of market dynamics and technological advancements, they empower innovative HealthTech companies and strategic investors to navigate complex transactions and achieve their growth ambitions. www.nelsonadvisors.co.uk
#NelsonAdvisors #HealthTech#MedTech#DigitalHealth #HealthIT #Cybersecurity #HealthcareAI #FemTech#ConsumerHealth #Mergers #Acquisitions #Partnerships #Growth #Strategy #NHS #UK #Europe #USA #Canada#Commonwealth#CorporateDivestitures #VentureCapital #PrivateEquity #Founders #SeriesA #SeriesB #Founders #SellSide #TechAssets #Fundraising #BuildBuyPartner #GoToMarket #PharmaTech #Genomics
Nelson Advisors
Hale House, 76-78 Portland Place, Marylebone, London, W1B 1NT
Meet Nelson Advisors @ Events in 2026
Digital Health Rewired > March 2026 > Birmingham, UK
NHS ConfedExpo > June 2026 > Manchester, UK
HLTH Europe > June 2026, Amsterdam, Netherlands
HIMSS AI in Healthcare > July 2026, New York, USA
Bits & Pretzels > September 2026, Munich, Germany
HealthInvestor Healthcare Summit > September 2026, London, UK
World Health Summit 2026 > October 2026, Berlin, Germany
HLTH USA 2026 > October 2026, USA
Global Health Exhibition 2026 > October 2026, Riyadh, Saudi Arabia
Web Summit 2026 > November 2026, Lisbon, Portugal
MEDICA 2026 > November 2026, Düsseldorf, Germany
Leaders in Health Summit 2026 > November 2026, London, UK
Venture Capital World Summit > December 2026, Toronto, Canada
Meet Nelson Advisors @ Events in 2027
Digital Health Rewired > March 2027 > Birmingham, UK
Barclays Health Elevate > March 2027, London, UK
NHS ConfedExpo > June 2027 > Manchester, UK
HLTH Europe > June 2027, Amsterdam, Netherlands


Comments